“The Younger You Are, the Better Medical Insurance Is” Is a Complete Myth! Three Traps Life Insurance Agents Don’t Tell You About—and the New Way to Choose Coverage


〈“It’s Better to Sign Up While You’re Young” — This is a Standard Sales Pitch Everyone Has Heard at Least Once, but Taking It at Face Value Could Cost You Several Million Yen.
In fact, locking yourself into insurance at an early age lacks rationality for three reasons: “Inflation could reduce the future value of your coverage to practically nothing,” “You could make more money by investing the premiums you save through the new NISA,” and “Japan’s High-Cost Medical Expense Benefit System means you can get through medical expenses with cash on hand.”
We asked former insurance company employee and financial planner Kenji Matsuura about the industry’s closely guarded calculations of the real costs and benefits, as well as the new medical insurance strategy for avoiding unnecessary premiums.〉
———
Medical insurance is the best-selling type of life insurance product. Because it is so widely sold, there are plenty of people who say they were glad they had it, as well as plenty who say having it was a waste of money. Should you get medical insurance? Is there a way to get better value from it? Here, I’ll explain the reality of medical insurance.
First, let’s look at the number of medical insurance policies sold across the life insurance industry. The number of new contracts refers to contracts newly acquired by 41 life insurance companies over one year (April 2025 to March 2026), while the number of policies in force refers to valid contracts held by those 41 life insurance companies.

Medical insurance had 2.87 million new contracts and 46 million policies in force in FY2025, making it the most widely sold product category among those offered by life insurance companies on both counts. The fact that so many people have it undoubtedly means it is a popular product. However, a popular product is not necessarily a good product. Depending on a person’s financial situation and the times they live in, it can be either a good or a bad product. Here, I’ll explain three points that could make it a bad choice.
1_Could inflation turn your coverage into worthless paper?
Japan has returned to an era of interest rates, with both deposit and loan rates rising, while prices are also increasing. When interest rates are rising, it is desirable to keep the term of money you deposit short, while locking in long-term fixed rates on money you borrow before rates rise further. So how should we think about insurance products?
Some insurance products have interest rates that are fixed by design, while others have rates that fluctuate. Variable-rate products can respond to inflation, but fixed-rate products cannot. While fixed rates were advantageous during the deflationary era, in an era of inflation, the value of the coverage steadily declines.
Medical insurance sold in Japan falls into the fixed category. So while a daily hospitalization benefit of ¥10,000 may provide sufficient coverage today, in 10 years it may only be worth ¥5,000 in today’s terms. In 50 years, it could be worth only about ¥1,000 in today’s terms. If that happens, the policy could become virtually useless, little more than a worthless piece of paper, making all those years of diligently paying premiums feel futile.
2_Would you be better off investing through the new NISA?
No one knows when or where they might become ill or injured. When treatment is necessary, you don’t want to have to choose not to receive it because you don’t have the money. You can prepare for medical expenses without taking out medical insurance. The idea is to save the money that would otherwise go toward insurance premiums, invest those funds, and build up money for medical expenses and other costs in case something happens.
Looking at hospitalization and outpatient treatment rates in Ministry of Health, Labour and Welfare statistics (graph below), young people rarely require either hospitalization or outpatient care, while the rates rise sharply once people reach old age, particularly from their 70s onward, along with their medical expenses. If you can invest your money until then, someone in their 20s has more than 40 years available for investment. Even contributing just ¥5,000 a month continuously could allow you to accumulate several million yen.

Some degree of financial literacy is necessary to invest successfully and generate returns, so this is not something everyone can do. However, young people have a considerable amount of time available for investment, which puts them in an advantageous position.
In recent years, amid the major push to shift from savings to investment, more people have been managing their assets through NISA accounts. It is entirely possible to prepare funds efficiently through investments instead of insurance.
3_Are cash and the high-cost medical expense benefit system enough?
Japan’s public health insurance includes the High-Cost Medical Expense Benefit System, which places a monthly cap on medical expenses. Therefore, unless you opt for treatment outside the public insurance system, you will not face unlimited medical expenses.
The cap varies depending on income, but for someone with an average income, it is around ¥100,000 per month. Depending on the health insurance plan you are enrolled in, additional benefits can reduce your medical expenses even further.
There are also costs outside medical expenses, such as charges for a private hospital room and transportation to and from medical institutions. But unless something particularly serious happens, wouldn’t ¥1 million be enough? If you have around ¥1–2 million in spare cash on hand, you will rarely find yourself in serious difficulty even without medical insurance.
The psychology and behind-the-scenes reality of life insurance saleswomen
Life insurance products can be sold by licensed life insurance solicitors, including sales employees of life insurance companies (such as life insurance saleswomen), employees of insurance agencies, and employees handling customer services at banks and securities firms.
Since solicitors are doing a job, they naturally pursue the interests of their company and their own income. Most solicitors make recommendations that are optimal for their clients, but unfortunately, some put themselves first. Therefore, the insurance you are recommended is not necessarily the best product for you.
It is important to have at least a basic understanding of insurance yourself and to compare and consider recommended policies from your own perspective. If doing this on your own is difficult, consulting a financial planner as a kind of second opinion is also a good option.
The new medical insurance strategy for avoiding losses

All insurance products are approved products and are based on the principle of equivalence between income and expenditure, so at the time they are launched, there are no products that generate huge profits for insurance companies or products that operate at a loss. There is no particular advantage to being young, either. However, if society changes significantly after a product is launched, the balance between income and expenditure can be disrupted, potentially turning some products into highly profitable ones and others into loss-making products.
For example, as Japan’s population has grown older and people have lived longer, fewer policyholders than insurance companies had anticipated have died. As a result, insurance payouts were lower than expected and insurers’ profits increased. This created room for insurers to lower premiums, and they have reduced premiums when revising their products.
As for medical insurance, when the novel coronavirus first emerged in 2020, insurers began paying hospitalization benefits even when policyholders did not actually enter a hospital. However, the subsequent waves of infections resulted in enormous payouts, causing insurance companies to suffer massive losses.
More recently, hospitalization lump-sum benefits have become more common in response to the trend toward shorter hospital stays. However, an increase in fraudulent claims has led to considerably stricter restrictions on eligibility than when these products were first introduced.
What I want to emphasize is that if you want to get insurance that offers good value, you should not simply follow the advice of an insurance solicitor. Instead, anticipate changes in medicine and insurance and in society as a whole—such as the declining birthrate and aging population, the financial condition of the public health insurance system, shorter hospital stays, and advances in medical technology—find insurance that you consider suitable, and maintain that coverage carefully. When society changes later, it will likely turn out to be a valuable insurance policy.
Young people shouldn’t rush to pay their insurance premiums
When you take out medical insurance, you become obligated to pay premiums. If you are hospitalized or undergo surgery for the purpose of treating an illness or injury, you become entitled to receive benefits.
If inflation continues, the value of money will steadily decline. But if both the premiums you pay and the benefits you receive decline in value at the same rate, there is, in a sense, no real gain or loss. From the policyholder’s perspective, the problem is when only the value of the benefits they receive declines. To avoid this, you should not force yourself to pay off your premiums over a short period.
Particular attention should be paid to policies in which young people pay the premiums for whole-life medical insurance over a short period, such as 10-year payment plans or plans that are fully paid by age 60. Paying premiums over a short period means each individual premium payment is higher, placing a greater burden on the household budget and potentially leaving you insurance poor. Once you finish paying, you may feel a weight lifted from your shoulders, but young people should prioritize investing in themselves for the future instead.
An FP explains the true role of insurance
Everyone naturally wants to gain rather than lose money, but it is important to understand that insurance should not be viewed in terms of whether you gain or lose financially.
For example, a certain number of people do not have vehicle coverage under their auto insurance—the type of coverage that pays out when their own vehicle is damaged and needs repairs. There are various reasons for not having it, such as, “If my car breaks down, I’ll just scrap it instead of repairing it,” “If I use my insurance, my rating will drop and my premiums will go up, so it’s difficult to use,” or “I don’t get into accidents.”
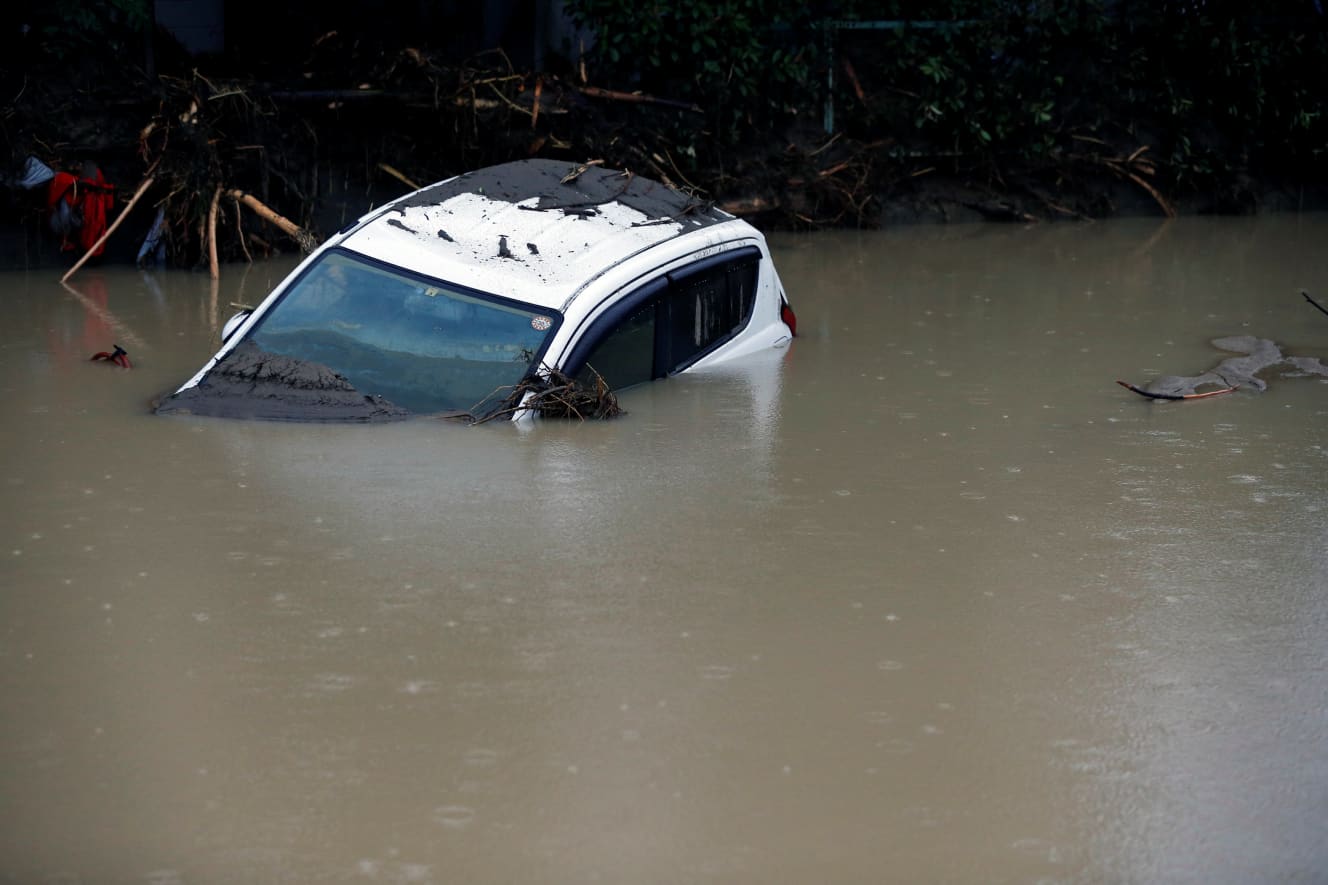
But even if you never get into an accident, your car could be submerged in a flood caused by heavy rain. If the car can no longer be driven and you bought it with a loan, you still have to keep making the payments. If you then purchase a new car, you could end up having to make two sets of payments.
Imagine the panic you would feel if you had no insurance. The same applies to a home that has neither fire insurance nor earthquake insurance. Especially when it comes to large compensation claims involving other people, being uninsured could potentially leave you financially ruined.
Medical insurance provides less coverage than fire or auto insurance, but if you become ill or injured and do not have the money to pay for treatment, your life could potentially be derailed. Therefore, people without sufficient savings should have appropriate insurance coverage. Even if nothing happens and you end up simply paying premiums without receiving any benefits, that is simply part of living in modern society.
By: Kenji Matsuura PHOTO: Afro (2nd photo)